
Payday loans can provide quick cash when you need it most, but choosing the wrong lender can trap you in a cycle of debt and hidden costs. We at Financial Canadian believe that finding immediate payday lenders you can trust requires knowing exactly what to look for and what to avoid.
This guide walks you through the red flags that signal predatory lending, how to verify a lender’s legitimacy, and the concrete steps to compare your options fairly.
Red Flags to Avoid When Choosing a Payday Lender
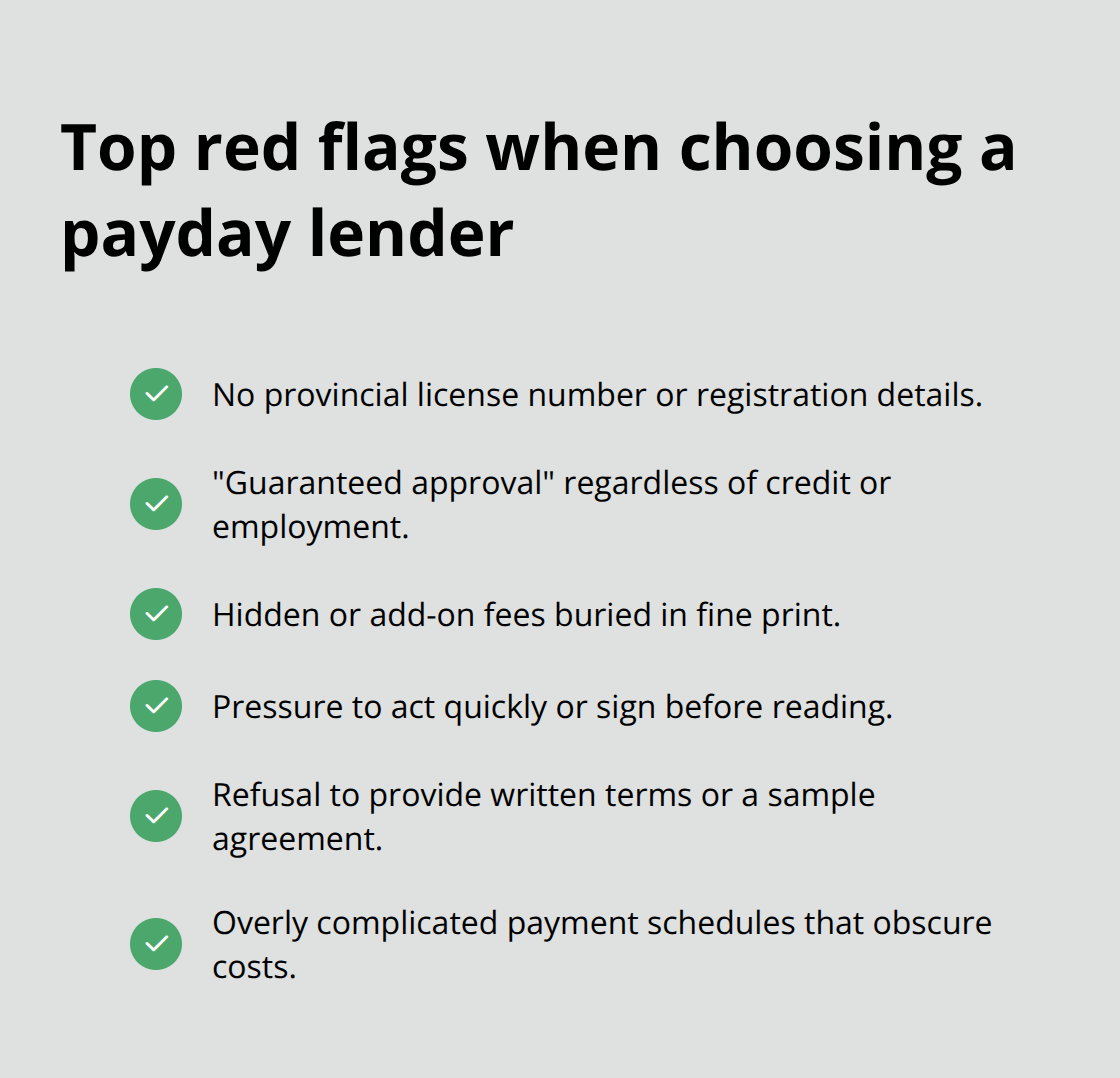
Lenders Without Proper Licensing or Registration
Predatory lenders operate in plain sight, and they rely on borrowers who are desperate or uninformed. The first red flag is a lender operating without proper provincial registration. In Canada, payday lenders must be licensed through their provincial financial regulatory body. Alberta requires registration through the Fair Trading Act, Ontario through the Payday Loans Act, and British Columbia through the Consumer Protection Act. If a lender cannot provide their license number or registration details, walk away immediately.
Unrealistic Promises and Guaranteed Approval Claims
Any lender guaranteeing approval regardless of credit history or employment status is lying. Legitimate lenders assess your ability to repay because responsible lending protects both parties. Guaranteed approval statements exist only to lure borrowers into traps. These promises signal that the lender prioritizes volume over your financial wellbeing, which means they’ll extract maximum fees from your desperation.
Hidden Fees and Unclear Terms
Hidden fees destroy the entire premise of short-term borrowing. Federal regulations cap payday loan interest rates at $14 per $100 borrowed in all provinces, but this applies only to transparent, registered lenders. Some operators bury fees in fine print or describe them as optional add-ons. You should receive a clear breakdown of the total cost before signing anything.
How to Spot Deceptive Practices
Check whether the lender discloses their interest rate and all fees upfront in writing. Vague language about costs, payment schedules that seem unnecessarily complicated, or pressure to act quickly all signal danger. A trustworthy lender gives you time to read and understand every term and answers questions directly. If a lender resists providing written terms or rushes you through documents, that’s a deliberate tactic to prevent you from spotting unfavorable conditions.
Request a sample loan agreement before committing (most legitimate operators provide this without hesitation). If the lender refuses or claims you don’t have time, that’s confirmation they’re operating outside legitimate business practices. Your financial safety depends on catching these warning signs before money changes hands. Once you’ve identified which lenders meet basic legitimacy standards, the next step involves verifying their credentials through official channels.
How to Verify a Payday Lender’s Legitimacy
Check Provincial Financial Regulatory Bodies
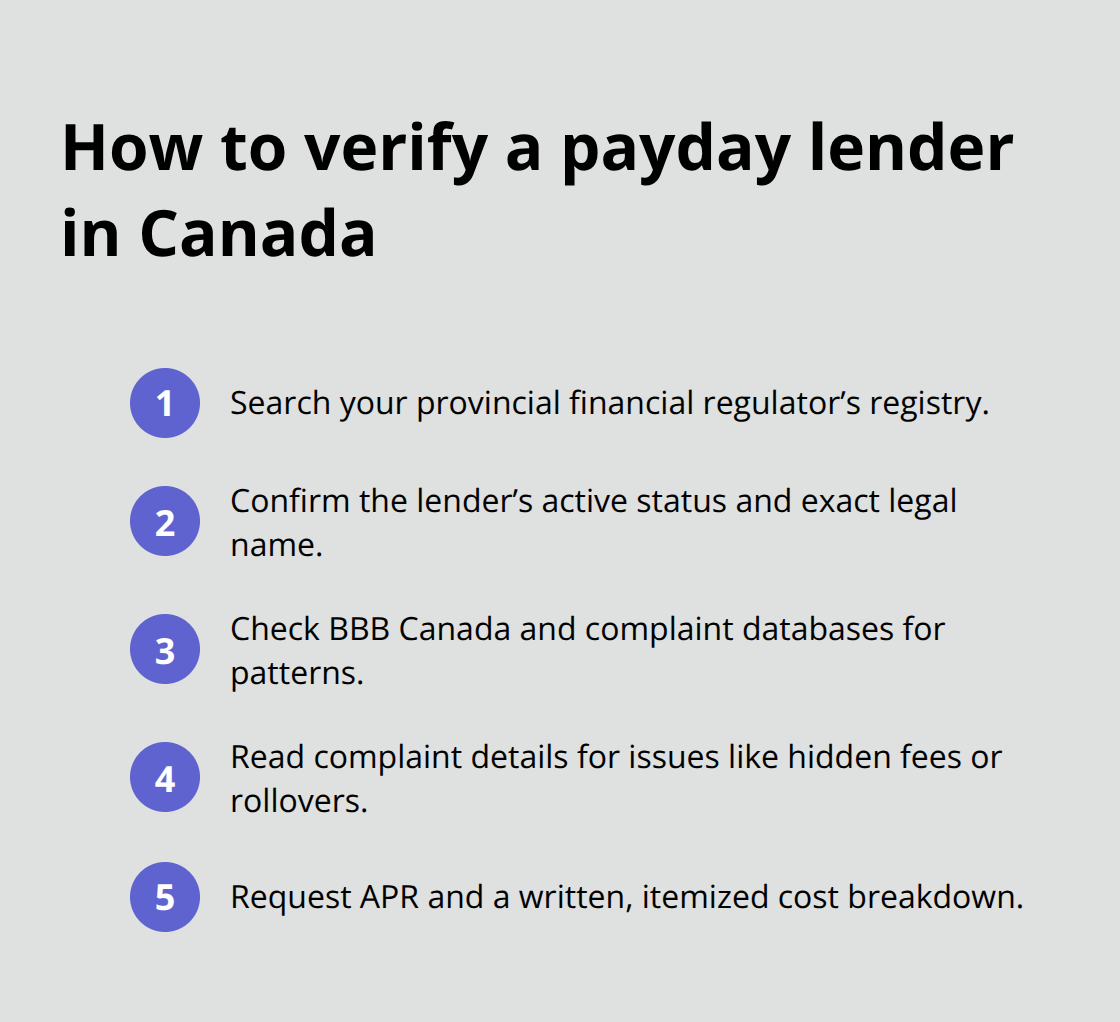
Start with your provincial financial regulator because they maintain the only authoritative list of legitimate payday lenders. In Ontario, contact the Financial Services Regulatory Authority, which publishes a searchable registry of licensed lenders on its website. Alberta’s registry operates through the provincial government’s Fair Trading Act compliance database. British Columbia maintains its list via the Financial Institutions Commission. These registries are free to search and take less than two minutes to confirm whether a lender holds active status.
If a lender’s name doesn’t appear in your province’s official registry, that operator is illegal and you should report them to your provincial consumer protection office immediately. Many borrowers assume that professional-looking websites mean legitimacy, but appearance means nothing without official registration.
Review Customer Feedback and Complaints
Customer complaints reveal patterns that individual reviews miss. Check the Financial Consumer Agency of Canada complaint database, which tracks unresolved disputes filed against financial institutions including payday lenders. Search your lender’s name on the Better Business Bureau Canada site to see complaint frequency, response rates, and resolution history.
The BBB rates businesses from A+ down to F, and payday lenders with ratings below B indicate systemic problems. Read specific complaints rather than just scanning star ratings because you’ll find details about hidden fees, aggressive collection tactics, or rollover traps that numbers alone won’t show. A lender with zero complaints across multiple platforms is rare but possible; a lender with dozens of unresolved complaints is a clear signal to move on.
Confirm Interest Rates and Fee Transparency
Interest rates and fees require direct comparison because lenders quote them differently. Request the annual percentage rate (APR) from each lender in writing, not just the fee per hundred dollars borrowed. A lender charging $15 per $100 borrowed on a two-week loan translates to roughly 390% APR, which is legal but aggressive.
Legitimate lenders provide this calculation without resistance because transparent operators have nothing to hide. Compare total repayment amounts across all options before committing, and reject any lender unwilling to provide written cost breakdowns in advance. Once you’ve narrowed your choices based on legitimacy and cost, the next step involves comparing how quickly each lender can fund your loan and what flexibility they offer in repayment terms.
Comparing Payday Lenders to Find the Best Option
The cheapest payday lender isn’t always the best choice, and the fastest approval doesn’t guarantee you won’t regret the decision later. Comparing payday lenders requires looking at three concrete factors that directly impact your financial situation: the total amount you’ll repay, how much flexibility you get if circumstances change, and how quickly the money actually reaches your account. Most borrowers focus only on the interest rate and miss the variables that matter most.
Assess Total Cost of Borrowing
Start with calculating the total repayment amount for each lender you’re considering, not just the fee percentage. A lender charging $14 per $100 borrowed on a $500 loan costs you $70, but another lender might charge $15 per $100 and cost you $75. That $5 difference seems minor until you realize some lenders add processing fees, verification fees, or e-transfer charges that can add another $10 to $25 to your actual cost.
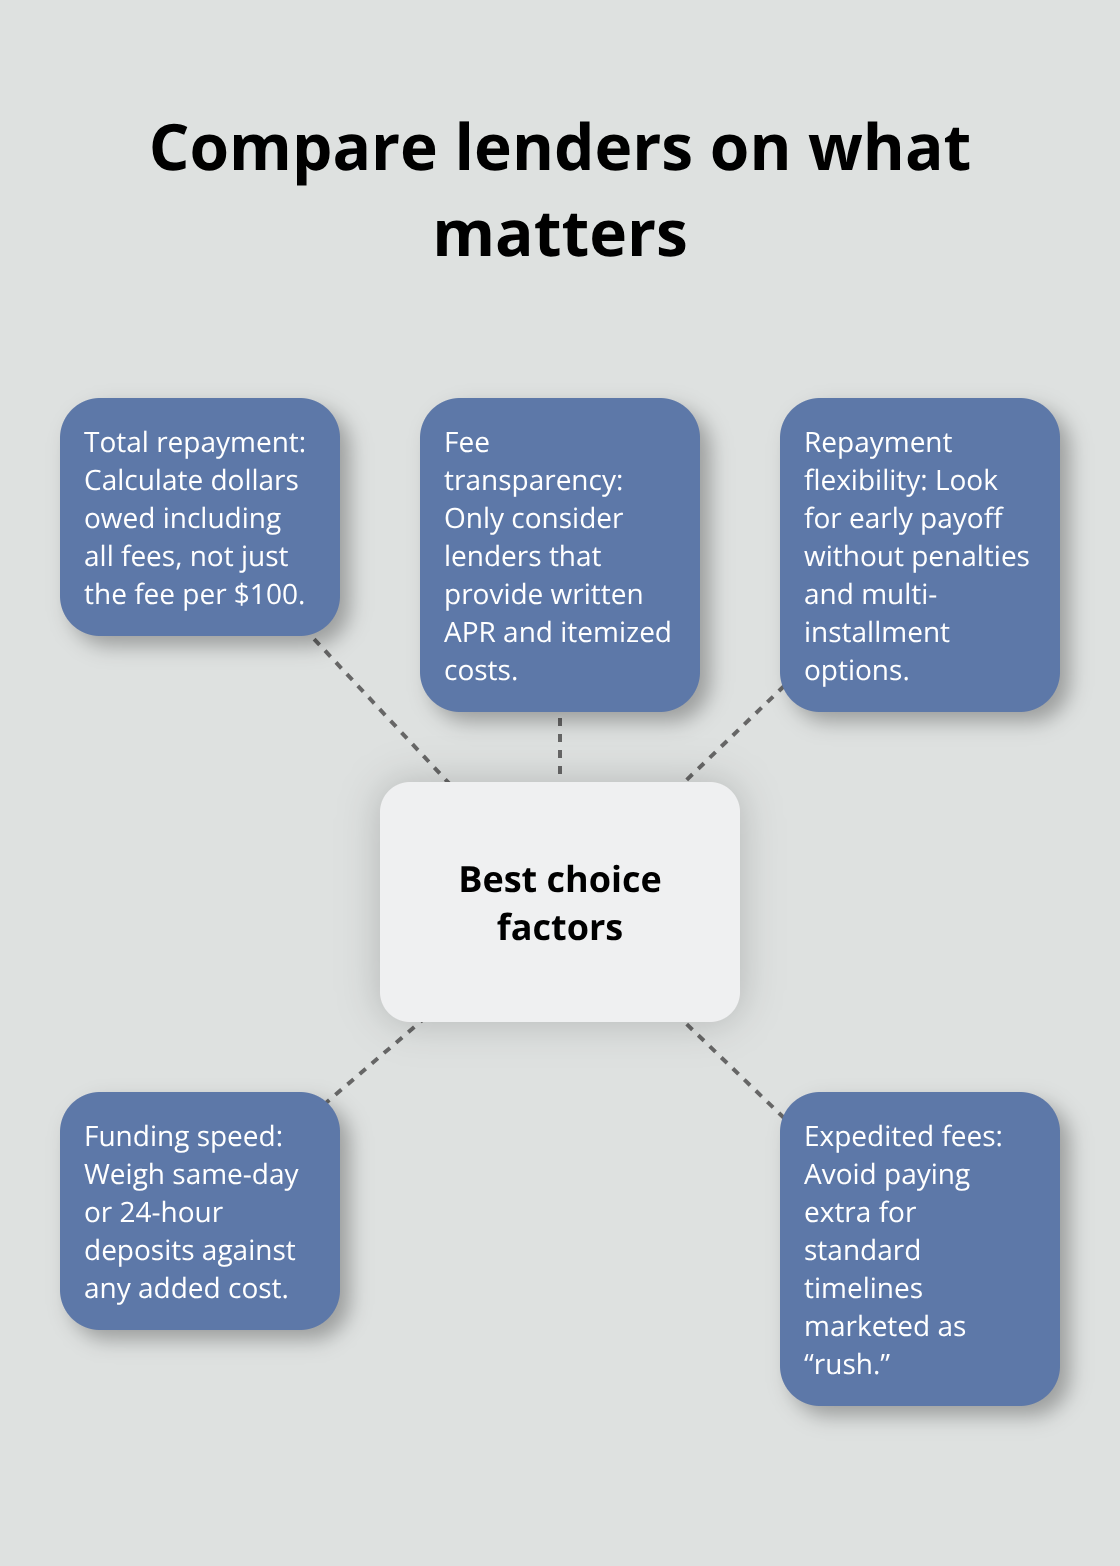
Request the final dollar amount you’ll owe, including every charge, then compare apples to apples. The Canadian Payday Loan Association reports that the average payday loan in Canada carries a two-week term, but repayment flexibility matters enormously if your paycheck arrives late or an unexpected expense hits before you planned to repay.
Evaluate Repayment Terms and Flexibility
Repayment flexibility is where predatory lenders make their real profit. A lender offering only rigid two-week terms forces you into rollover traps if you can’t repay on time, meaning you pay another full fee to extend the loan another two weeks without reducing the principal. Reject any lender that makes rollover easy or encourages it as a solution.
Legitimate lenders allow early repayment without penalty and offer options like splitting repayment across multiple smaller payments if you request it. Ask each lender whether you can repay early without losing any portion of the fee you paid, and whether they offer flexible repayment schedules for borrowers facing temporary income disruptions. A lender willing to work with you on repayment terms signals they care about your ability to actually repay rather than just maximizing fees through rollover cycles.
Look for Fast Approval and Funding Processes
Funding speed varies wildly between lenders, from same-day deposits to three to five business days. If you need cash today, a lender offering e-transfer within two hours is obviously superior to one requiring 48 hours, but only if the total cost remains reasonable. Some lenders charge premium fees for expedited funding, effectively adding another $15 to $30 to your repayment amount.
Calculate whether the speed justifies the extra cost by asking yourself how much you’d pay to solve your immediate cash problem. Most legitimate online lenders deposit funds within 24 hours without charging extra, so avoid any operator demanding additional fees for standard speed. Approval timelines also vary, with some lenders approving applications in minutes and others requiring a few hours to verify your employment and bank account details (the fastest approval means nothing if the lender then delays funding for days). Ask specifically how long after approval the money hits your account, and compare this timeline across all your options before making a final decision.
Final Thoughts
Finding trustworthy immediate payday lenders requires you to verify three non-negotiable criteria: official provincial registration, transparent fee disclosure, and reasonable repayment flexibility. Your provincial financial regulator maintains a free searchable registry that takes two minutes to check, while the Better Business Bureau Canada provides detailed complaint histories at no cost. These resources exist specifically to protect you, and using them before you apply for a loan represents the smartest decision you can make.
Due diligence before you borrow prevents the debt traps that destroy borrowers’ finances. Spending thirty minutes checking a lender’s registration status, reviewing their complaint history, and comparing total repayment costs across multiple operators will save you hundreds of dollars and prevent the rollover cycles that trap you in endless fees. The borrowers who end up trapped in payday loan debt almost always skipped this verification step because they felt desperate or rushed.
We at Financial Canadian help borrowers navigate lending decisions through responsive, user-friendly resources with integrated features and SEO optimization that reach Canadians who need this information most. The verification process outlined here works only if you actually access the tools and information available to you, which means having clear, accessible resources at your fingertips. Immediate payday lenders exist in every province, but only the registered ones will respect your financial wellbeing.



Leave a comment